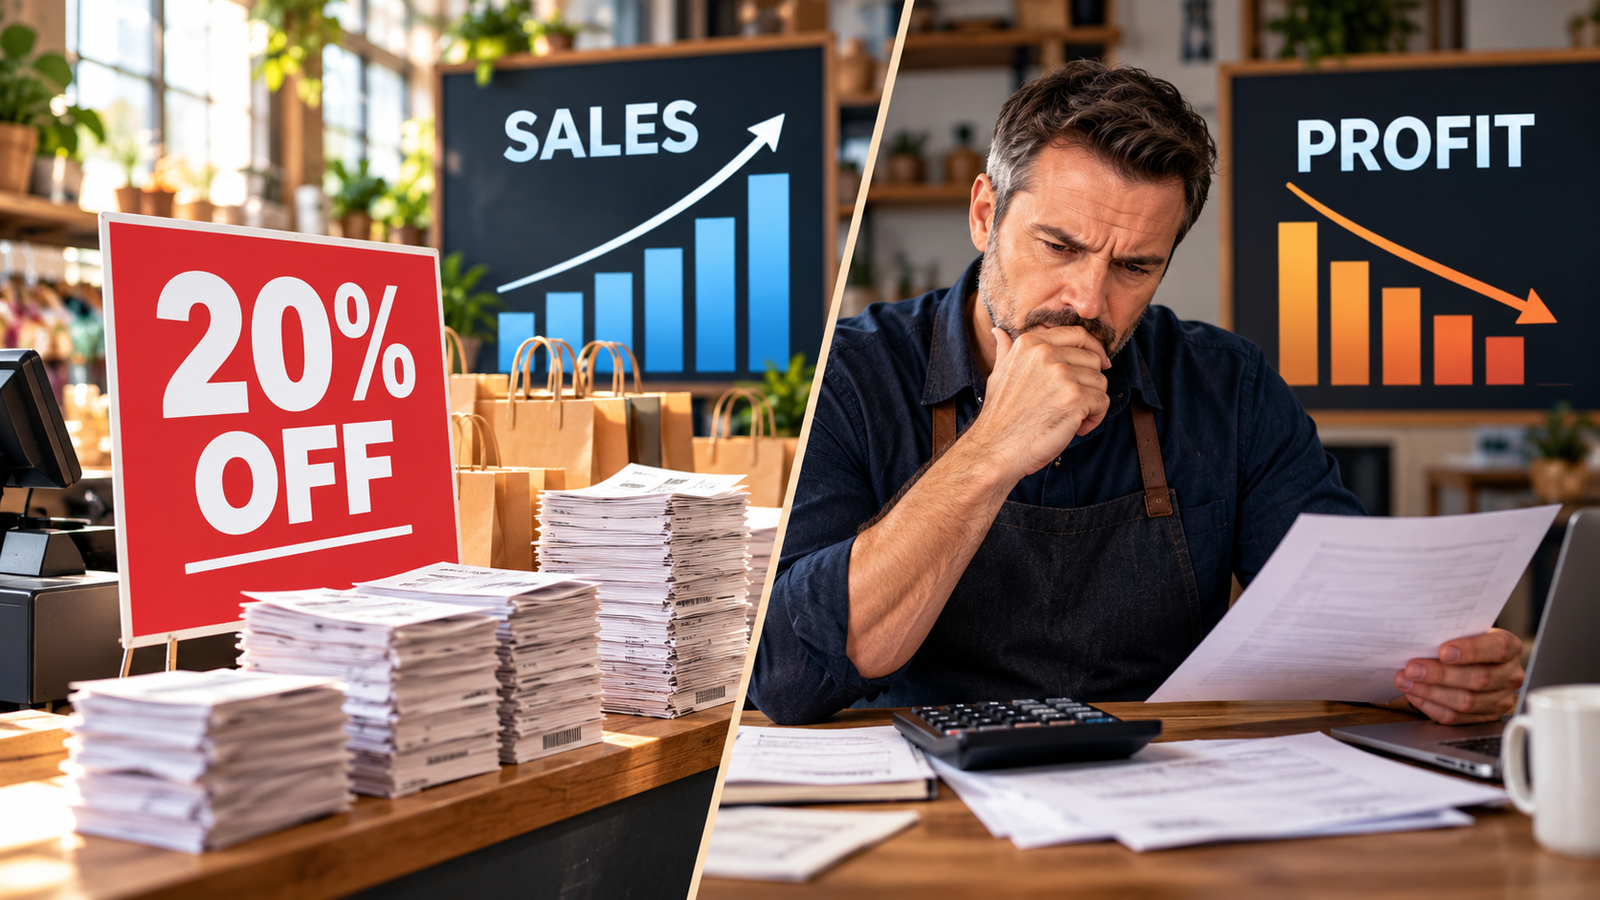
A promotion brings in more orders. The till is busy, customers are pleased, and the sales report is up. It looks like a success.
But at the end of the month, the business owner notices something uncomfortable: despite selling more, the money left to cover overheads and profit has fallen.
That can happen when a discount removes more of the contribution from each sale than the extra sales volume can replace.
A 20% discount does not simply reduce profit by 20%. Depending on the original margin and the cost of delivering each sale, it may cut the amount contributed by each sale by half—or more.
Before offering a discount, the useful question is not only “Will this attract more customers?” It is “How much more do we need to sell for the promotion to make financial sense?”
The difference between a discount and the margin it removes
Suppose a shop sells a product for $100. The variable costs of buying, preparing and fulfilling each sale total $60. Before paying rent, administration and other fixed overheads, that sale contributes $40.
This $40 is its contribution per unit: the selling price less costs that change with each unit sold. It helps cover the business’s fixed costs and, once those are covered, contributes to profit. This follows the contribution-margin framework explained in the OpenStax managerial accounting textbook.
Now offer a 20% discount. The customer pays $80 rather than $100, but the illustrative $60 variable cost remains unchanged.
At full price: $100 sale − $60 variable cost = $40 contribution
With 20% off: $80 sale − $60 variable cost = $20 contribution
The customer saved $20. But the business gave up $20 of the $40 it previously retained to cover fixed costs and profit. In this simplified example, the discount has removed 50% of contribution per sale.
If it now takes twice as many transactions to produce the same total contribution, the promotion faces a much greater hurdle than its headline suggests.
Worked example: sales rise 20%, but contribution falls 25%
Consider three possible months for the same product. Before the promotion, the shop sells 100 units at $100 each. A 20%-off promotion increases unit sales to 150. A more successful promotion doubles sales to 200 units.
| Measure | Normal month | 20% off: +50% units | 20% off: +100% units |
|---|---|---|---|
| Units sold | 100 | 150 | 200 |
| Selling price each | $100 | $80 | $80 |
| Variable cost each | $60 | $60 | $60 |
| Revenue | $10,000 | $12,000 | $16,000 |
| Total contribution before fixed costs | $4,000 | $3,000 | $4,000 |
At 150 units, the promotion looks impressive: sales revenue rises from $10,000 to $12,000. That is a 20% increase in turnover.
But contribution falls from $4,000 to $3,000. The business now has 25% less available to pay its fixed costs and generate profit, before allowing for any additional promotion costs.
Only when the shop sells 200 discounted units—twice the original quantity—does it recover the same $4,000 contribution as the normal month. Even then, extra advertising, overtime or other promotion-specific costs might leave it worse off.
All figures are illustrative, not results from an actual business. The example assumes a constant $60 variable cost per unit, unchanged product mix and fixed costs within the relevant volume range.
How many more sales would a discount really require?
You can answer this using the contribution from each sale, without sophisticated software.
Units needed to match existing total contribution
Current total contribution ÷ contribution per discounted unit
In the example above: $4,000 ÷ $20 = 200 units. Compared with 100 normal units, the required increase is 100%.
For a single product with constant variable cost per unit, you can also estimate the extra volume from the original contribution margin expressed as a percentage of the original selling price:
Required percentage increase in units = Discount percentage ÷ (Original contribution margin percentage − Discount percentage) × 100
This formula applies only while the discount is smaller than the original contribution margin and the underlying cost assumptions hold. If the discount wipes out contribution entirely, selling more units cannot recover the lost contribution; if it makes the contribution negative, extra sales deepen the loss.
Small-looking discounts can require substantial extra volume
The table below assumes the same product normally sells for $100 and has a 40% contribution margin before discounting.
| Discount | New contribution per $100 item | Extra units required to maintain contribution |
|---|---|---|
| 5% | $35 | 14.3% |
| 10% | $30 | 33.3% |
| 15% | $25 | 60% |
| 20% | $20 | 100% |
| 25% | $15 | 166.7% |
These are mathematical thresholds, not predictions of customer behaviour. They tell you the sales lift required to replace the contribution given away. They do not tell you whether a particular promotion will achieve that lift.
The five-question discount decision test
1. Are we measuring revenue, gross profit or contribution?
Start with the right number. Revenue is the money customers pay. Gross profit is revenue less cost of goods sold. Contribution subtracts the variable costs attributable to the sale and indicates how much remains for fixed costs and profit.
Which number is useful depends on your business. A product seller may need to account for packaging, card fees and per-order shipping. A service business may need to count the additional paid hours, supplies or subcontractor costs involved in delivering more work. Never mix definitions across the comparison.
If you’re unsure whether the problem is really pricing or work being given away, read Are Your Prices Too Low—or Is Your Business Giving Away Too Much Work?.
2. How many extra sales can we realistically deliver?
An increase in orders is only helpful if you can supply those orders reliably. Imagine a service business offering 20% off but using evenings or additional contractors to handle the volume. The new labour costs may make the original calculation too optimistic.
Capacity matters just as much as demand. A promotion that strains delivery can create delays, rework or dissatisfied customers. Our article Should You Hire More Staff—or Fix the Way Your Business Works First? examines the distinction between capacity and process problems.
3. Are we giving the discount to customers who would have bought anyway?
This is one of the most important questions. A discount offered to everyone may include customers who were already willing to pay full price. In that case, the business has reduced its earnings on sales that might have occurred regardless.
The true test is incremental business: sales that would not have happened without the promotion. You cannot determine that from the number of discounted orders alone.
Compare with a sensible baseline, taking seasonality and recent trends into account. Consider whether an offer should target a particular product, quieter period or identifiable customer need instead of discounting the entire business.
4. Does the promotion bring the type of customer we want?
A short-term boost is not necessarily a long-term gain. Some promotions introduce customers who return at full price, while others attract people who only buy at heavy discounts.
If you are relying on repeat purchasing to justify a lower first-sale contribution, examine actual retention and repeat-purchase margins. Don’t assume all new customers will be profitable later. See Why Don’t Customers Come Back? for a practical retention diagnosis.
5. What other work or costs will this create?
Extra advertising, printed promotions, platform fees, refunds, overtime, packaging, delivery, stock shortages and support requests can all change the economics.
A small business should also look at cash flow. More discounted sales may require buying additional stock or paying suppliers before customer receipts arrive. The promotion can look successful on the sales report while increasing pressure on available cash.
Our article Profitable but Short of Cash? looks at the timing of money coming in and going out.
A practical 30-minute discount worksheet
Use a spreadsheet to model an ordinary week or month alongside a proposed promotion. Keep the time periods comparable.
| Input or calculation | Normal trading | Proposed discount |
|---|---|---|
| Selling price | $_____ | $_____ |
| Variable cost per sale | $_____ | $_____ |
| Contribution per sale (price − variable cost) | $_____ | $_____ |
| Number of sales | _____ | _____ |
| Total contribution (sales × contribution) | $_____ | $_____ |
| Promotion-specific fixed costs | $_____ | $_____ |
| Contribution after promotion-specific fixed costs | $_____ | $_____ |
The target is not simply to make the discounted column larger on turnover. It is to see whether the relevant contribution left after the extra costs is stronger than the normal-trading alternative.
If you offer several products or services, calculate each group’s contribution separately. A promotion that changes the product mix can produce a very different result from a single-product model.
When discounting may still be the right decision
This isn’t an argument that every discount is harmful. Discounting can make sense when it solves a clearly identified business problem and the numbers support the decision.
For example, a carefully limited promotion may help move stock that is becoming obsolete, fill otherwise unused capacity where variable costs are low, introduce a product to suitable new customers, or secure a customer relationship with credible future value.
But each of those has a different objective. Clearing perishable or ageing inventory may justify a lower contribution than ordinary trading because the relevant alternative could be even worse. Filling unused service capacity may make sense if extra work truly can be delivered without displacing full-price bookings or increasing fixed costs.
The analysis should reflect the real alternative, including any genuinely avoidable storage, spoilage or idle-capacity costs. The simple 20%-off example is a starting point, not a universal decision rule.
If the promotion fails the test, what should you fix first?
The wrong response is not necessarily to eliminate every discount. It’s to identify why the business feels it needs one.
If customers don’t understand the value offered, the priority may be how the service is explained. If conversion is weak because quotations are slow, the priority could be follow-up. If costs have crept up, the priority may be fulfilment or purchasing. If existing customers have stopped returning, the priority may be customer experience.
More marketing is not always the answer either. Before increasing traffic or promotion spending, it can help to test whether the problem is really attracting enquiries or converting them into customers. Read Do You Need More Leads—or Better Conversion?.
What matters is diagnosing the underlying constraint before selecting a solution that looks attractive but could deepen the problem.
The question to ask before the next sale
Before displaying a discount sign, run the numbers for the outcome you need. Know the contribution at the current price, the contribution after the discount, the additional unit sales required, and whether your team and cash flow can support the expected demand.
A successful promotion is not necessarily the one with the busiest checkout. It is the one that improves the business’s actual result.
If several issues are competing for your attention—pricing, marketing, capacity, retention and cash flow—learn how a Business Growth Assessment helps identify the ONE business priority that deserves attention first. If you want a free starting point, learn what the eight-question Business Priority Check includes before deciding whether to invest in a deeper review.
All numerical scenarios are hypothetical and simplified for educational purposes. Actual margins depend on costs, product mix, returns and the relevant business alternatives. Consult a qualified financial professional where needed.