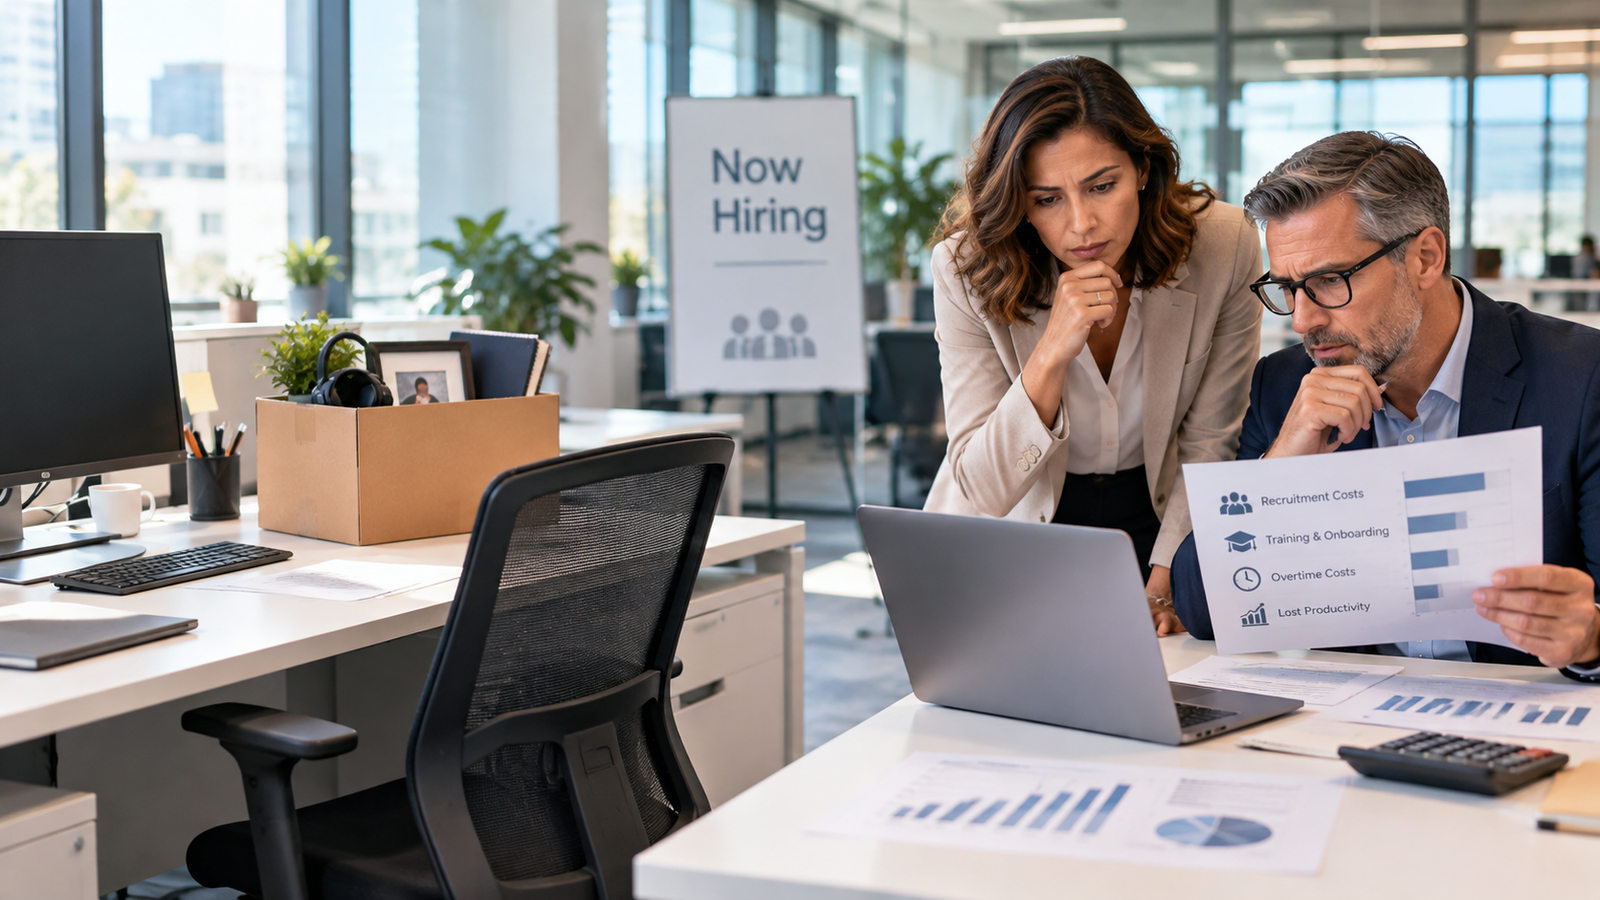
A good employee leaves. You advertise the vacancy, interview applicants and bring someone new into the business. If the replacement starts on roughly the same salary, it can seem as though the financial damage was limited to an advertisement or recruitment fee.
But the cost of employee turnover in a small business can extend well beyond recruitment. Other employees may cover shifts, a manager spends hours hiring and training, and jobs may take longer or need correcting while a replacement learns the work.
Before spending money on a new retention initiative, it helps to answer two questions: What did this departure actually cost us? And what was the main reason it happened?
What counts as the cost of replacing an employee?
Employee turnover is the departure of staff over a period. Some turnover is normal or even useful; the business question is whether preventable departures are creating costs or disruption that deserve priority attention.
The CIPD’s employee turnover and retention guidance recommends understanding why people leave before choosing retention measures. That matters particularly in smaller organisations, where one departure may disrupt an entire team.
A practical replacement-cost calculation should separate cash expenses from the value of time and contribution lost:
- Recruitment cash costs: job advertisements, agency fees, screening tools and any paid assessments.
- Management time: writing the job description, reviewing applications, interviewing and arranging references.
- Vacancy cover: additional overtime, temporary staffing or contractors needed to keep work moving.
- Induction and training: paid trainer time, a colleague’s time and new starter training resources.
- Rework: avoidable corrections, mistakes and repeated tasks while the new employee learns.
- Unfilled demand: contribution from work the business could have delivered but did not, if capacity was genuinely lost.
Not every business incurs every item. Some are direct cash expenses; others are estimates of opportunity cost. Keep them separate so you do not mistake an estimate for money that has left the bank.
A small-business employee replacement cost example
Imagine a ten-person service business replacing a departing employee. The manager records the following costs over the vacancy and first weeks of the new hire.
| Cost | Illustrative basis | Amount |
|---|---|---|
| Recruitment advertising | Actual cash expense | $300 |
| Manager’s hiring time | 10 hours × $35/hour | $350 |
| Temporary overtime cover | Additional payroll cost | $800 |
| Colleague’s onboarding time | 12 hours × $30/hour | $360 |
| Avoidable corrections | Extra materials and labour | $240 |
| Work not delivered | Estimated lost contribution | $600 |
| Total estimated replacement cost | $2,650 | |
This is a hypothetical example, not a benchmark or a real BGA client result. The two time items represent the value of productive work diverted, not automatically additional cash payments. The $600 in lost contribution assumes different work from the jobs covered by overtime; counting the same missed work twice would exaggerate the result.
The manager may have spent only $1,340 in obvious cash outlays (advertising, overtime and correcting work). But the wider estimate helps explain why replacing someone can be more disruptive than the recruitment invoice suggests.
Published cost estimates vary substantially by role. For context, Gallup has described replacement costs ranging from half to twice an employee’s annual salary in its US research. Those figures are not a fixed rule for every small business. Your own records are more useful for deciding what to do next.
How to calculate your own employee turnover cost
Start with the most recent departure, not a hypothetical average across the whole company. Use a simple spreadsheet with four columns: item, quantity, unit cost and total.
- Define the period. Include the vacancy and the new employee’s initial learning period. Do not compare different-length periods without adjustment.
- Record direct cash costs. Use payroll, invoices and job advert receipts where possible.
- Value diverted time carefully. If an owner spent eight hours interviewing, record the hours and an explicit estimate of what that time was worth. This is not necessarily eight extra hours of payroll.
- Calculate lost contribution, not lost revenue. If you genuinely had to decline a profitable job, deduct the costs you avoided by not doing it. Do not count the entire sale price as lost profit.
- Check for double counting. If overtime fulfilled a job, you cannot also treat that same job as lost. If a training hour is already included in a contractor invoice, do not add it again.
Cash recruitment + extra cover + additional training or correction costs + estimated productive time diverted + lost contribution on genuinely undelivered work = total estimated replacement cost.
Use a range when the opportunity-cost figures are uncertain. A lower estimate using verifiable cash outlays and an upper estimate including well-reasoned time and contribution costs is often more honest than one apparently precise number.
How to calculate a small-business employee turnover rate
Replacement cost tells you the likely impact of one departure. Turnover rate tells you how often departures happen.
Number of employees who left during 12 months ÷ average number of employees during that period × 100
If one person leaves a business with an average of ten employees, its annual turnover rate is 10%. If two leave, it is 20%. In a small team, one departure changes the percentage sharply, so examine the underlying number, the role and the circumstances—not only the headline rate.
Separate voluntary resignations from redundancies or other departures. Look for a pattern in a particular role, manager, season or stage of employment before assuming you have a company-wide problem.
Does higher pay always solve the problem?
No single answer fits every business. Pay may be an important reason someone leaves, and an unfair or uncompetitive offer needs direct attention. But compensation is not the only possible constraint.
Some employees leave because of unpredictable hours, unmanageable work, limited development, a poor working relationship or an environment in which they cannot do their jobs properly. The CIPD’s retention guidance recommends investigating the causes rather than applying the same fix to everyone.
It is worth asking whether good employees are spending a large part of their week compensating for broken processes. If tasks repeatedly return for clarification, the business may be making capable people feel ineffective. Our related article, Is Your Business Waiting for You?, explains how routine approvals can delay work even when staff are capable of completing it.
Equally, a new job title or motivational workshop cannot compensate for an unsafe workplace, persistent unfair treatment or genuinely excessive workloads. Those issues call for proper management action, not a quick productivity exercise.
The 30-day small-business retention diagnosis
The goal of a short review is not to prove you can prevent every resignation. It is to identify one evidence-based change worth testing before rolling out an expensive, company-wide scheme.
Days 1–7: record the cost and the friction
Calculate the latest replacement cost using the worksheet above. Then identify where work regularly gets delayed, repeated or escalated. Ask managers to note recurring operational obstacles, not employees’ personal details. If a departure is sensitive, keep any information confidential and appropriate to your employment obligations.
Days 8–14: listen before diagnosing
Invite staff to share what makes good work difficult and what one change would help most. Review exit interview themes if they are available and appropriate, but remember that a single comment is not proof of a wider pattern. Be prepared to hear that the problem is pay, management behaviour or workload—not merely inefficient systems.
Days 15–21: choose one change
Look for an issue supported by more than one signal. It might be repeated weekend overtime, unanswered questions about responsibility, or a handover that routinely creates rework. Decide who owns the fix and what evidence would show improvement. If the problem is unclear authority, see Should You Hire More Staff—or Fix the Way Your Business Works First?
Days 22–30: test and review
Implement one manageable improvement. Review the leading signals you can observe soon: avoidable overtime, repeated errors, missed handovers, approval delays or employee feedback on the specific obstacle. An annual turnover rate will not reliably move in a single month, so do not claim that one short test has proved retention improved. Continue tracking departures and feedback over time.
Five questions before spending on a retention programme
- Do we know the actual cost of the most recent departure, including time and disruption?
- Are repeated resignations concentrated in a role, team or working condition?
- Have we heard directly from employees, rather than assuming what matters to them?
- Which single change addresses the strongest cause we can verify?
- What would we measure to decide whether to expand, revise or stop that change?
Good induction matters, too. The CIPD’s induction guidance describes a structured introduction as an opportunity to help new employees settle into their roles and understand the work. If new starters leave quickly, investigate what happens after the offer is accepted as well as how the business recruits.
Find the cost, then identify the priority
Employee turnover costs can be larger than they first appear, but the answer is not automatically to offer a bonus, introduce new software or start a big culture programme. First measure the impact. Then investigate the real reason people are leaving. Finally, address the issue that evidence suggests will make the greatest difference.
That is the same principle behind Business Growth Assessment: find the ONE area that deserves attention first, rather than spend money on several possible solutions at once.
If you are uncertain whether staffing, management processes, sales or cash flow is the constraint your business most needs to address, start with the free Business Priority Check. It is designed to help you identify where closer examination may be most useful.
All monetary figures in the worksheet are illustrative. This article offers general business-management information, not employment-law, accounting or legal advice. Employment obligations vary by location.