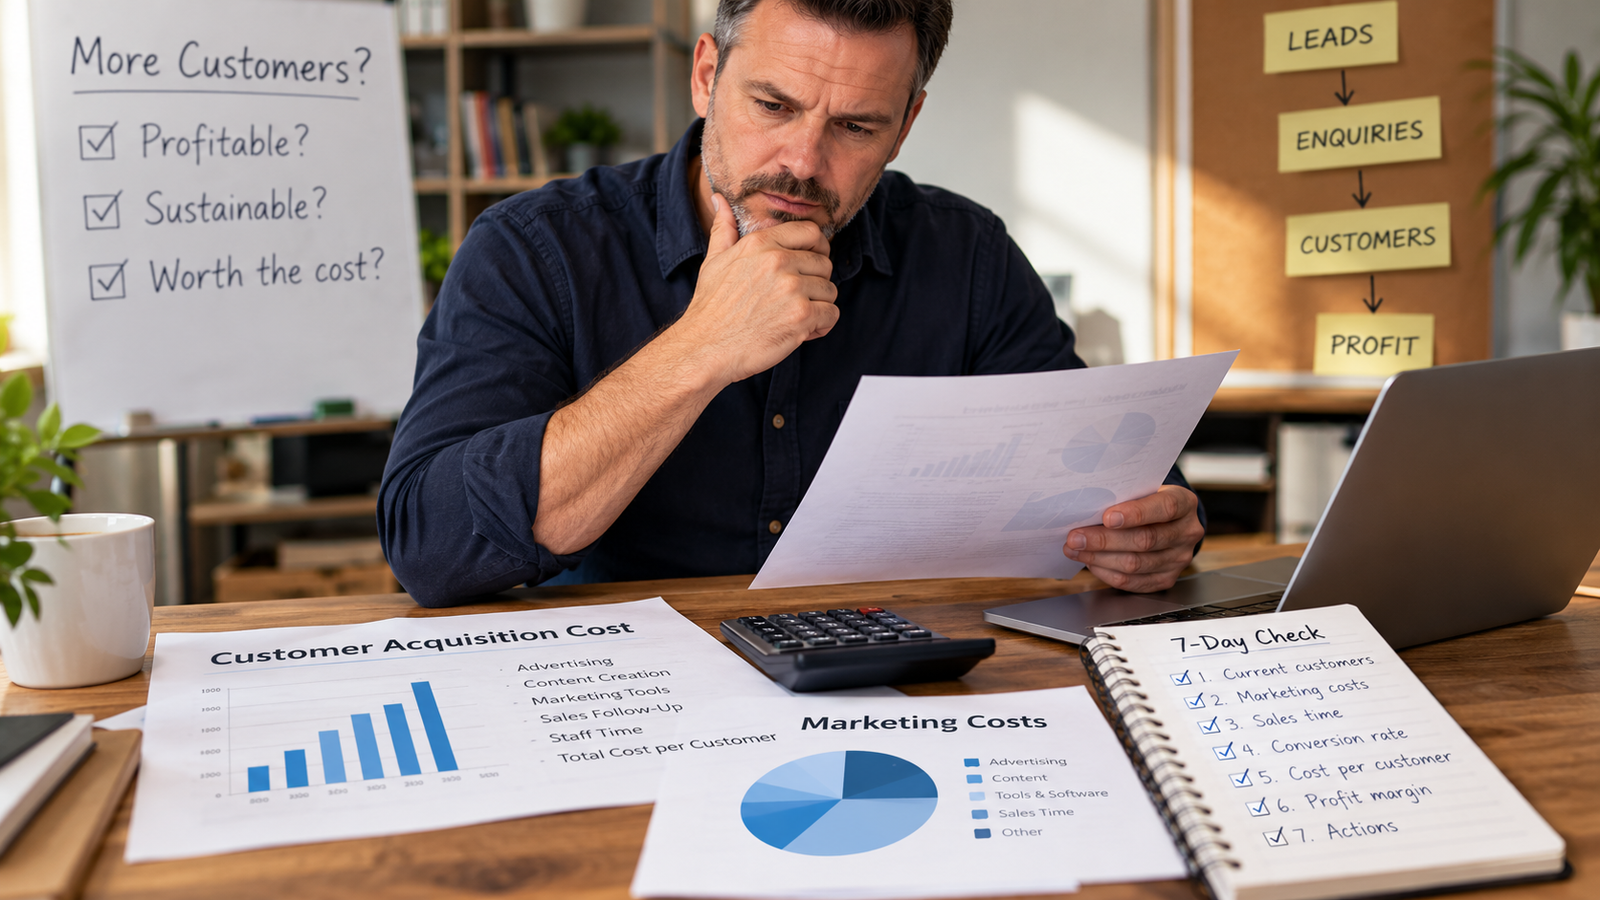
A business owner spends $800 on advertising and wins 20 new customers. The calculation looks encouraging: $40 to attract each customer.
But the owner also paid for content, subscriptions and other marketing work. Someone spent hours answering enquiries and following up leads. Perhaps the owner did that work personally, so it never appeared on an invoice.
Once those costs are considered, the business might have spent far more than $40 to win each customer. It may even be acquiring customers at a cost that leaves very little money from their first purchase.
This is why customer acquisition cost (CAC) deserves attention. It reveals what the business spends to turn strangers into paying customers—not simply what it spends on advertisements.
It also helps answer a more useful question than “Do we need more marketing?”: Are we attracting the right customers, at a cost the business can sustain?
What is customer acquisition cost?
Customer acquisition cost is the total sales and marketing cost of acquiring a new paying customer over a defined period, divided by the number of new customers acquired during that period.
For example, if a company spends $1,900 on acquiring customers over a month and wins 20 genuinely new customers, its average CAC is $95.
The calculation is straightforward; choosing the right inputs is where mistakes occur. You need to decide what the business spent, which customers are genuinely new and whether the costs and customers belong to comparable periods.
This follows the full-cost approach outlined in Shopify’s guide to customer acquisition, which cautions against counting advertising spend alone.
Why an advertising dashboard can give an incomplete answer
Advertising platforms are useful for measuring clicks, leads and conversions, but they usually do not know the full cost of selling. An owner may look at a campaign, see $800 spent and 20 customers gained, then conclude that a new customer costs $40.
That leaves several questions unanswered. Who wrote the advertisement? Who created the images? Who paid for the software? Who replied to enquiries, produced quotations or followed up people who had not yet bought?
If those activities are necessary to acquire customers, excluding them can give an artificially attractive result.
This does not mean every expense belongs in CAC. Delivery materials, manufacturing and after-sale service should ordinarily be analysed as costs of fulfilling the sale, rather than counted again as acquisition costs. A useful calculation distinguishes the cost of winning a customer from the cost of serving one.
A worked example: the difference between $40 and $95
Consider an illustrative service business that gained 20 new paying customers in a month. Its customer acquisition activity involved:
| Customer-acquisition activity | Monthly cost |
|---|---|
| Paid advertising | $800 |
| Content and creative production | $450 |
| Sales enquiry and follow-up time, valued at an estimated labour cost | $500 |
| Attributable software and tools | $150 |
| Total acquisition cost | $1,900 |
| New paying customers | 20 |
| Customer acquisition cost | $95 each |
These figures are hypothetical, not results from an actual client. Owner or staff time may be an economic estimate rather than an additional cash payment. Keep cash costs and imputed time costs separate when planning cash flow.
The advertising dashboard suggested $40 per new customer. Once the wider work was included, the estimated full acquisition cost rose to $95.
That does not automatically make the marketing unsuccessful. It tells the owner that the question needs to be investigated properly.
A $250 sale does not necessarily make a $95 acquisition cost worthwhile
Suppose the average first order brings in $250. After paying $140 in direct costs to deliver that order, the business has $110 left as a contribution towards acquisition costs and overheads.
Deduct the illustrative $95 CAC, and the first order leaves just $15 before other operating costs and taxes.
This $15 is not the same as net profit. The business may still need to cover rent, administration and other operating expenses not already included. Equally, a customer who returns for future purchases may generate additional contribution without the same acquisition expense.
For a business with reliable repeat purchasing, the first transaction may not be the entire economic story. But future orders should be supported by evidence of actual retention and margins—not optimistic assumptions about what a customer might someday buy.
A one-off service with little repeat business faces a different decision from a subscription or regularly replenished product. There is no useful universal CAC target for all business models.
The seven-day customer acquisition cost check
You do not need a sophisticated marketing platform to get started. Set aside a week to gather the right information. Use the previous 30 to 90 days of sales and cost records for the figures, choosing a window that suits your sales cycle.
Day 1 — Count real new customers
Start with the number of people or organisations who became paying customers for the first time in your chosen period. A lead, enquiry, free trial or quotation is not the same as a new customer.
If one business customer placed four orders, that normally counts as one newly acquired customer—not four. Keep existing and returning customers separate so you do not confuse repeat sales with acquisition.
Day 2 — List the direct marketing expenditure
Record paid advertisements, promotions, lead-generation fees, external marketing providers, creative production and the relevant portion of marketing software.
If a cost supports both customer acquisition and something else, record a reasonable allocation and note the assumption. Avoid double-counting discounts as both reduced revenue and a full acquisition expense without a consistent accounting treatment.
Day 3 — Measure the work required to turn interest into a sale
Count the time spent responding to leads, preparing quotes, giving demonstrations, calling prospects and following up. This can be significant in service businesses where the owner handles the selling personally.
For practical decision-making, create two views: a cash CAC based on actual acquisition payments, and a full economic CAC that also values owner time at a reasonable replacement or opportunity cost. Label the estimates clearly.
Day 4 — Calculate the average CAC
Add the relevant costs and divide by the number of new paying customers. Keep the same period and counting rules for every comparison.
If your typical sales cycle is long, do not assume the customers who signed this month were created by this month’s marketing. Look at a longer period or match marketing activity to customer cohorts where records allow.
Day 5 — Look at the contribution from each first sale
For your typical new customer, take the first sale price and subtract the direct costs of delivering the product or service. Then compare the remaining contribution with CAC.
If the first transaction cannot recover acquisition costs, investigate whether repeat business reliably makes up the difference—and how much working capital is needed before it does.
Day 6 — Look for differences between sources of customers
Separate customers who came through advertising, referrals, organic search, local visibility, networking or other sources when your records make that possible.
Do not assume a “free” referral or social media lead costs nothing. Referral rewards, networking hours, content work and follow-up still consume resources. Nor should every acquisition cost be assigned to the last channel a customer clicked; some customers encounter several channels before buying.
Day 7 — Choose one improvement to test
The most useful outcome is not a colourful marketing report. It is identifying where the acquisition process is losing the most value, so you can decide what deserves attention first.
Choose one change that addresses the strongest evidence. Track it for a reasonable period and check both the acquisition cost and the quality of customers gained.
Use this simple customer acquisition review table
A spreadsheet can show which assumptions you are using and make it easier to repeat the test. A basic template looks like this:
| Marketing source | Acquisition costs | New customers | Estimated CAC | First-order contribution before CAC |
|---|---|---|---|---|
| Paid advertising | $_____ | _____ | $_____ | $_____ |
| Referrals | $_____ | _____ | $_____ | $_____ |
| Organic search | $_____ | _____ | $_____ | $_____ |
For each row, estimated CAC is acquisition costs divided by new customers. If a channel has no new customers in the period, do not divide by zero: note it as “not calculable for this period” and investigate whether its results are delayed or its performance is weak.
Only allocate shared expenses by channel where you have a sensible method. Otherwise, calculate the blended CAC for the whole business first. A precise-looking number based on guesses is not an improvement.
Five different findings can point to five different priorities
1. You are paying to attract the wrong enquiries
If advertising generates lots of leads but few suitable prospects, review targeting and the promise made in the message. Paying for more traffic could magnify the problem.
2. Good enquiries are being lost before the sale
If interested prospects are not getting timely answers, are confused by your quotation process or disappear during follow-up, the priority could be sales conversion—not expanding the marketing budget. Our article Do You Need More Leads—or Better Conversion? explores that distinction.
3. Each sale contributes too little
You could acquire customers efficiently but still struggle if pricing, discounts, unexpected work or fulfilment costs consume the margin. Read Are Your Prices Too Low—or Is Your Business Giving Away Too Much Work? for a way to investigate.
4. Customers buy once and do not return
A high acquisition cost may be recoverable over time if customers return profitably. But if they do not come back, the root problem could be delivery, expectations or ongoing customer experience. That is a different investigation from simply buying more advertising. See Why Don’t Customers Come Back?.
5. The owner is doing all the selling
When every enquiry requires an owner conversation, the immediate bottleneck may be time, unclear qualification or a missing process rather than an advertising expense. Counting the owner’s hours makes that dependency visible.
What if you have very few customers or unreliable records?
A new business may not yet have enough transactions for a stable CAC estimate. One customer won from an unusually successful referral—or one lost sale—can distort the average. In that situation, focus on keeping a simple record, checking actual direct costs and testing demand on a modest scale.
For a larger business, a monthly blended CAC can be a useful starting point, but it may hide important differences between customer types and channels. If different groups have different margins or repeat-purchase behaviour, compare them separately once the data is reliable.
Also remember that marketing is not the only investment required to make growth successful. If a company cannot deliver what it sells, additional customers can increase pressure on staff, customer experience and cash flow. Our sales-to-delivery handover test examines one common operational weakness.
Don’t decide to spend more until you know what more means
It’s easy to be persuaded by a bigger advertising reach, more clicks or a promising sales forecast. But the objective is not to buy activity. It is to acquire customers who contribute to a sustainable business.
Before you increase the budget, ask: How many genuine customers are we winning? What does winning them actually cost? What remains from their purchases? And where is the first constraint that makes the result weaker than it should be?
The answer may be better targeting. It may be faster follow-up, clearer pricing, stronger retention or a more reliable delivery process. Those are different problems, and each points to a different action.
The most important question isn’t how much marketing you can afford. It’s whether you know what the current marketing is really producing—and what deserves attention first.
If several areas of your business appear to need improvement, learn how a Business Growth Assessment helps identify the underlying business problem before committing more resources. For a preliminary perspective across more than marketing, explore the free Business Priority Check, personally reviewed and returned by email.
The dollar amounts in this article are illustrative examples, not results from actual clients. Acquisition cost calculations depend on accounting policies, attribution and time periods; consult your accountant for formal financial reporting or tax decisions.