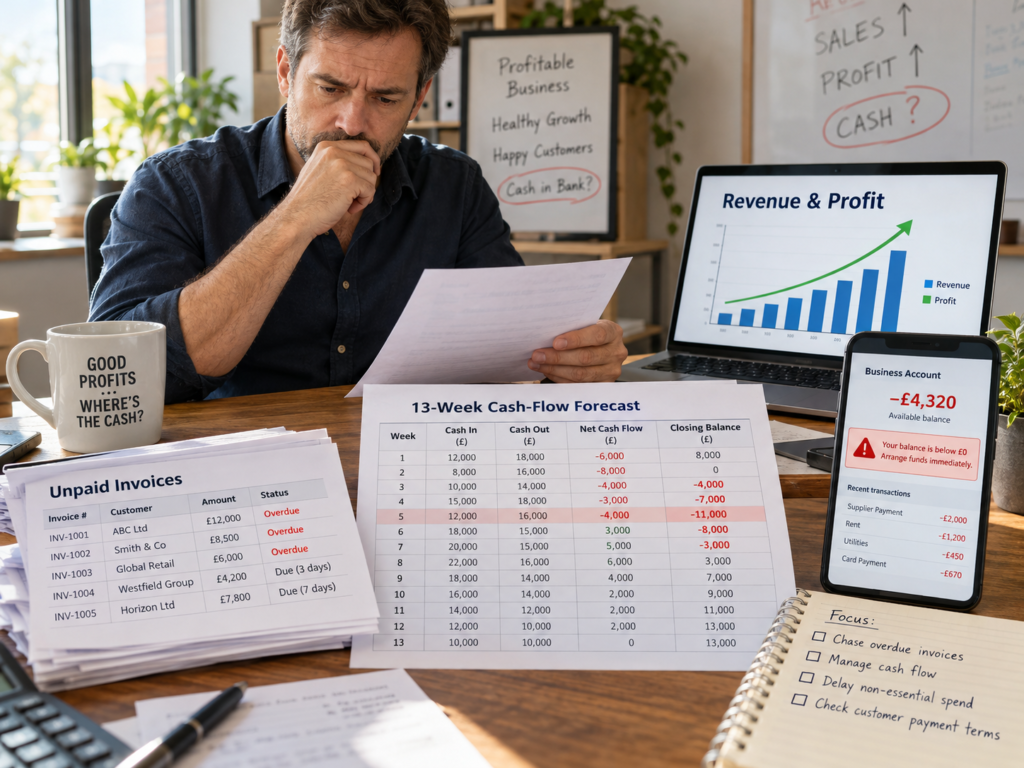
A business owner opens the monthly accounts and sees a profit. The team has been busy, sales are healthy and customers are buying. Yet the bank balance is uncomfortably low, suppliers are asking when they’ll be paid and payroll is approaching.
How can a business be profitable and still struggle to pay its bills?
Often, the answer is timing. A sale can be recorded before the customer pays. Meanwhile, wages, stock, rent and taxes may have to be paid much sooner. The business isn’t necessarily short of work. It may be short of cash at the moment it needs it.
Profit and cash flow answer different questions
Profit is broadly what remains after the relevant income and expenses are recognised in the accounts. Cash flow is the movement of money into and out of the business.
A profitable business can experience a cash shortage if customers pay slowly, stock ties up money or major bills fall due before incoming payments. The opposite is possible too: a healthy bank balance after a loan or large customer deposit does not necessarily mean the underlying business is profitable.
Neither measure replaces the other. The important question is whether the apparent financial problem comes from inadequate margins, the timing of payments, excessive cash tied up in operations, or a combination of these.
A simple example: the profitable month that creates a cash squeeze
Consider a hypothetical service business that invoices €20,000 in October. It expects €14,000 of associated costs, leaving €6,000 before other accounting adjustments and taxes. On paper, that looks encouraging.
But the customer has 60 days to pay. In the meantime, the business must cover €8,000 in wages and €4,000 in materials during October. The invoice will not pay those bills until the money actually arrives. If the business doesn’t have sufficient opening cash or other collections, it may struggle despite the apparently profitable job.
This is a simplified example, not a substitute for a proper profit-and-loss statement or cash-flow forecast. It illustrates one basic principle: the date a sale is made is not always the date the money becomes available.
Five places to look before blaming poor sales
- Unpaid customer invoices. Are customers paying according to agreed terms? Is anyone following up promptly when payments become overdue?
- Payment terms that don’t match. Are you paying suppliers within 14 days while customers pay you after 60?
- Work in progress. Are you paying staff and buying materials long before a job reaches its next billable milestone?
- Stock sitting on shelves. Has money been spent on inventory that isn’t yet turning into sales and receipts?
- Large predictable payments. Are taxes, insurance, annual subscriptions or seasonal costs missing from the owner’s short-term cash planning?
Some businesses genuinely need more sales or higher margins. But spending more on marketing will not necessarily solve slow collections or an unsuitable payment structure.
What your cash-flow spreadsheet might look like
Here is a simple starter layout. Enter the money you expect to receive and pay in the week it will actually move. The figures below are illustrative and follow the earlier example:
| Week | Opening cash | Expected receipts | Essential payments | Closing cash | Notes |
|---|---|---|---|---|---|
| 1 | €7,000 | €500 | €3,000 | €4,500 | Wages and materials |
| 2 | €4,500 | €500 | €3,000 | €2,000 | Supplier payment |
| 3 | €2,000 | €500 | €3,500 | –€1,000 | Projected shortfall |
| 4–13 | Continue with one row per week, carrying each closing balance into the next opening balance. | ||||
Spreadsheet formula: Closing cash = Opening cash + Expected receipts − Essential payments. The next week’s opening cash equals the previous week’s closing cash. Negative closing cash means a forecast funding gap; it does not mean an overdraft is available. In Excel or Google Sheets, put each of these headings in a separate column and extend the rows through week 13.
Try a 13-week cash timing review
Start with your current available cash. On a simple spreadsheet, create one column for each of the next 13 weeks. Then record expected incoming and outgoing payments for the week in which you realistically anticipate the money moving, not just when the invoice was issued.
- List expected receipts. Include outstanding invoices with realistic payment dates, known deposits and other reliable incoming amounts. Keep uncertain opportunities separate.
- List essential payments. Include payroll, rent, supplier payments, taxes, loan repayments and other commitments as they fall due.
- Calculate the weekly closing balance. Start with opening cash, add receipts and subtract payments; carry the result into the following week.
- Mark the lowest point. Identify when cash is likely to be tightest and what payments or receipts are driving that pressure.
- Update it weekly. Replace estimates with what actually happened and revise the dates that changed.
A forecast is a decision aid, not a guarantee. If the review indicates you may not be able to meet upcoming obligations, seek timely guidance from your accountant or a qualified financial adviser rather than waiting for the payment date.
Three questions to ask when the forecast looks tight
Which numbers are certain, and which are assumptions? An invoice that is contractually due next Tuesday is not necessarily cash you can depend on receiving that day. A prospective sale is even less certain. Make the distinction visible in your forecast.
What happens if a major customer pays two weeks late? Change that receipt date in a second version of the spreadsheet. If a modest delay creates a large shortfall, the business may need a stronger cash buffer or different commercial terms even when customers usually pay reliably.
Which decision can improve the position without creating a larger problem? Chasing overdue invoices, agreeing appropriate staged payments and scheduling discretionary spending are different responses. None should be chosen automatically: consider customer relationships, contractual obligations and the longer-term cost.
Choose the solution that matches the cause
If invoices are consistently overdue, clearer terms and a disciplined follow-up process might be the first priority. If a project requires significant spending before the first customer payment, staged billing or deposits may be worth considering, subject to what customers and contracts allow. If excess stock is absorbing funds, purchasing and inventory decisions may deserve attention.
Where the underlying issue is poor profitability, collecting invoices faster may only provide temporary relief. The business may need to examine pricing, delivery costs or uncharged work instead. Our article on pricing versus giving away extra work explores that distinction.
And if several issues are apparent at once, our guide to identifying the business bottleneck that deserves attention first helps separate the symptoms from the constraint.
Don’t solve a timing problem with the wrong investment
It can be unsettling to see profitable work alongside a shrinking bank balance. The instinct may be to chase more revenue, hire a salesperson or launch a new promotion. Sometimes those steps make sense. Sometimes they increase the amount of cash the business must spend before it collects another euro.
Before choosing the next improvement, establish whether the problem is how much money the business earns, how quickly it collects it, or how much it has to spend in advance.
The right diagnosis determines the right priority. To explore which area of your business deserves attention first, visit our Business Growth Assessment website and start with the free Business Priority Check.